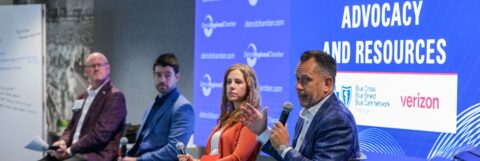
Yaniv Ribon pointed to an aging population, chronic conditions, higher medical prices, hospital consolidation, and expensive medications as major cost pressures. Rather than eliminating coverage, he encouraged employers to work with qualified advisors to compare provider networks, pharmacy benefits, copays, and other plan details.
Employers may also consider narrower networks, high-deductible or health savings account-compatible plans, virtual care, and stronger primary-care engagement. Ribon cautioned that every design choice involves tradeoffs, particularly for employees who may struggle to absorb higher out-of-pocket costs, making gradual implementation and clear communication important.
“I think about it as a hierarchy. Number one in that hierarchy is to choose the right network. A PPO network, or third provider organization, that is very broad [in coverage]. And an HMO, health maintenance organization, which tends to be a little bit more narrow, but certainly enough to provide the kind of access that your employees are looking for,” he said. “Just by moving from a PPO to an HMO, without changing benefits, an employer can see around a 20% reduction in their health insurance premiums.